Education Credits and Tax Benefits Before College
College tuition can qualify for a federal tax credit of up to $2,500 per student. Adults returning to school may qualify for a different credit, and families paying expenses before college have several tax benefits to consider. The key is to match each expense to the right rule and coordinate it with scholarships and education savings accounts.
The American Opportunity Credit Covers Four Years
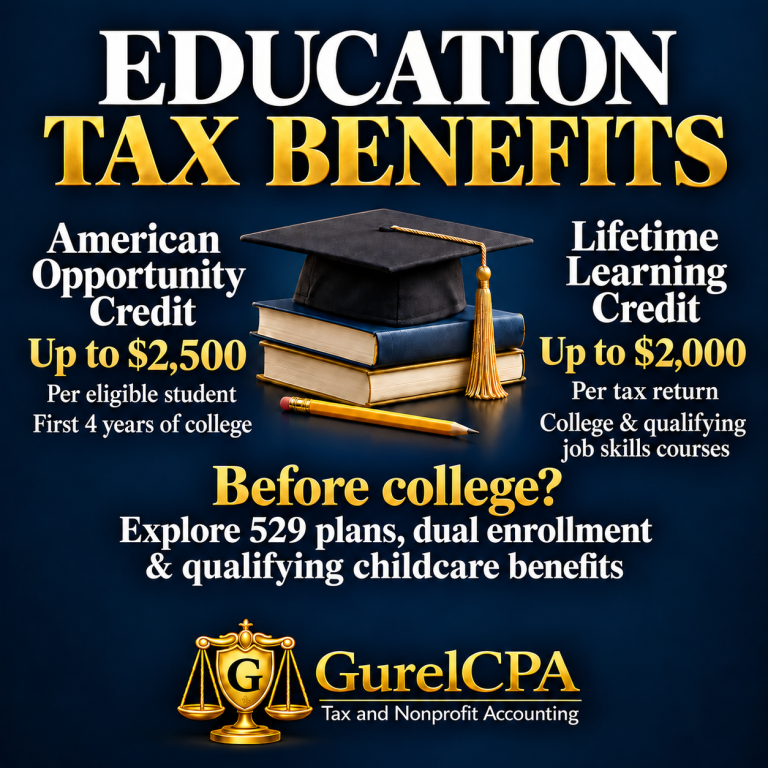
The American Opportunity Tax Credit applies to the first four years of postsecondary education. It can provide up to $2,500 per eligible student each year: 100% of the first $2,000 of qualifying expenses, plus 25% of the next $2,000. A family with two eligible college students could qualify for as much as $5,000.
The student must pursue a degree or other recognized credential and attend at least half-time for at least one academic period during the year. The student cannot have completed the first four years of postsecondary education before the year began, and the credit cannot have been claimed for that student in four previous tax years. A felony drug conviction can also disqualify the student. Eligible vocational and certificate programs can qualify.
Qualified costs include tuition, required enrollment fees, and books, supplies, and equipment needed for the course of study, even when purchased outside the school. Room and board, transportation, and insurance do not qualify. Up to $1,000 of the credit may be refundable, meaning it can be paid even when no federal income tax is owed. Special rules limit refunds for many students under age 24 who claim the credit themselves.
The Lifetime Learning Credit Supports Continuing Education
The Lifetime Learning Credit can cover undergraduate and graduate education, as well as qualifying courses to acquire or improve job skills. There is no limit on the number of years it can be claimed, and a student can qualify with just one course at an eligible institution. Half-time attendance and a degree program are not required. A private training course does not automatically qualify simply because it helps your career.
The credit equals 20% of up to $10,000 of qualified expenses, for a maximum of $2,000 per tax return. That limit applies to the whole return, regardless of how many students qualify. It is nonrefundable, so it can reduce federal income tax to zero but cannot generate a refund beyond the tax owed. Books, supplies, and equipment qualify only when payment to the institution is required for enrollment or attendance.
Income and Filing Rules Apply to Both College Credits
For either credit, the full amount is available when modified adjusted gross income is $80,000 or less, or $160,000 or less for married couples filing jointly. The credit decreases above those amounts and reaches zero at $90,000 or $180,000, respectively. Married taxpayers filing separately cannot claim either credit. These credits are available whether you itemize deductions or take the standard deduction.
For tax year 2026, new identification rules apply. The taxpayer claiming the credit must have a Social Security number valid for work and issued before the return’s due date, including extensions; the student must also have a qualifying SSN. For a joint return, the IRS describes the taxpayer requirement as applying to you or your spouse. Families that previously relied on an ITIN should check eligibility before expecting a credit.
A New Scholarship Donation Credit Begins in 2027
Beginning January 1, 2027, a new federal scholarship tax credit may provide up to $1,700 for qualifying cash donations to approved scholarship-granting organizations. States must elect to participate and submit qualifying organizations to the IRS. This is a credit for donors supporting K–12 scholarships, not a credit for paying your own child’s tuition. It does not apply to donations made in 2026.
What About High School and Younger Students
There is no general federal education credit for paying ordinary elementary or high school tuition, tutoring, school supplies, or homeschool expenses. The two college credits apply to qualifying postsecondary education. However, families may benefit from the following rules.
College courses during high school. Tuition paid to an eligible college for dual-enrollment courses may qualify for the Lifetime Learning Credit if the course and other eligibility requirements are met. The American Opportunity Credit requires enrollment in a program leading to a degree or recognized credential; simply earning college credit while in high school does not establish eligibility. If the school or state pays the full cost, there may be no family-paid expense to claim.
529 education savings plans. Beginning in 2026, up to $20,000 per beneficiary per year can be withdrawn for qualified K–12 expenses, combined across all of that beneficiary’s 529 accounts. Qualified expenses now extend beyond tuition to certain curriculum materials, books, qualifying tutoring outside the home, standardized and college-admission tests, AP exams, dual-enrollment fees, and specified therapies for students with disabilities. Provider and expense requirements still apply.
A 529 withdrawal is a savings benefit, not a tuition tax credit. Earnings can be withdrawn free of federal tax when the withdrawal qualifies. Contributions receive no federal deduction. Some states offer contribution deductions or credits, and state treatment of withdrawals can differ. Match withdrawals with expenses in the same calendar year.
Coverdell education savings accounts. These accounts can also provide tax-free earnings for qualifying elementary, secondary, and college expenses. Total annual contributions are limited to $2,000 per beneficiary across all contributors. Income and age restrictions apply. Contributions do not qualify for a federal deduction or education credit.
Preschool and care before or after school. The Child and Dependent Care Credit may apply when care for a qualifying child under age 13 allows a parent to work or look for work. Preschool costs may qualify, even when the program includes learning activities. Kindergarten and higher-grade tuition do not qualify, but separately identified before- or after-school care may. Earned-income and other eligibility rules apply.
Coordinate Expenses Before Claiming a Credit
The same student cannot receive both college credits in the same year, although a family may claim the American Opportunity Credit for one student and the Lifetime Learning Credit for another. The same expense cannot support an education credit and a tax-free 529 or Coverdell withdrawal. Tax-free scholarships and other education assistance also reduce the expenses available for a credit.
For example, a family eligible for the full American Opportunity Credit might reserve $4,000 of otherwise qualifying tuition and course-material costs for that credit, then use 529 funds for other qualifying expenses. Certain college room-and-board expenses can qualify for 529 withdrawals even though they do not qualify for either college credit. The allocation should be planned before withdrawals are made.
When parents claim a student as a dependent, the education credit generally belongs on the parents’ return. Parents and students should coordinate their filings. Keep Form 1098-T, the school’s detailed account statement, receipts for course materials, scholarship information, and Forms 1099-Q for education-account withdrawals. Education credits are claimed on Form 8863; Form 1098-T alone may not show all qualifying expenses.
At GurelCPA, we can help you compare education credits and coordinate them with scholarships and savings withdrawals. Contact us before year-end or before making a major tuition payment so we can identify which expenses will qualify and who should claim them.
The article is meant for informational purposes only. Please contact me directly to discuss how this applies to your individual tax situation.