Foreign Earned Income Exclusion vs. Foreign Tax Credit
For U.S. taxpayers living or working outside the United States, foreign income does not mean freedom from U.S. taxes. The U.S. tax system taxes citizens and resident aliens on worldwide income, regardless of where they live.
Fortunately, the Internal Revenue Code provides two powerful tools to reduce or eliminate double taxation:
- The Foreign Earned Income Exclusion (FEIE)
- The Foreign Tax Credit (FTC)
While both are designed to prevent double taxation, they operate in fundamentally different ways. Choosing the wrong one can cost taxpayers thousands of dollars in unnecessary tax over time. Understanding the distinction between these two strategies is essential for proper international tax planning.
What Is the Foreign Earned Income Exclusion (FEIE)?
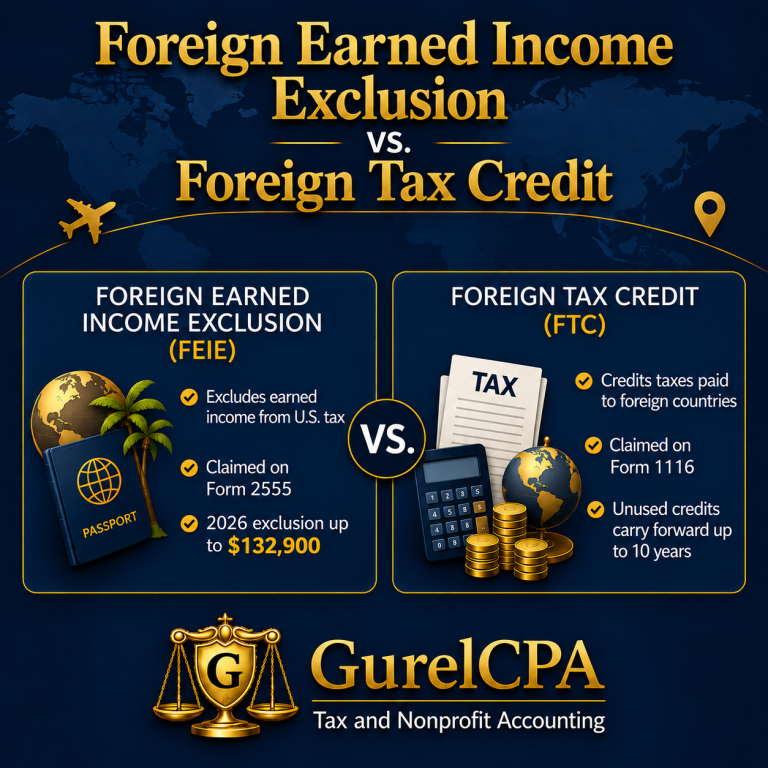
The Foreign Earned Income Exclusion allows qualifying taxpayers to exclude a portion of their foreign earned income from U.S. taxation.
Key features of the FEIE include:
- Applies only to earned income, such as wages, salary, and self-employment income
- Does not apply to passive income, such as interest, dividends, rental income, and capital gains
- Requires meeting either the Bona Fide Residence Test or the Physical Presence Test
- Must be elected by filing Form 2555
- For 2026, qualifying taxpayers may exclude up to $132,900 of foreign earned income. The exclusion amount is adjusted annually for inflation.
If a taxpayer qualifies, foreign earned income may be excluded from U.S. taxable income, reducing federal income tax.
However, an important exception applies to self-employed individuals. The Foreign Earned Income Exclusion generally does not eliminate U.S. self-employment tax. A Totalization Agreement between the United States and another country may affect which country's Social Security system applies, but the FEIE itself does not eliminate self-employment tax.
This is one of the most commonly misunderstood aspects of the FEIE.
The Foreign Housing Exclusion and Deduction
Taxpayers who qualify for the Foreign Earned Income Exclusion may also qualify for the Foreign Housing Exclusion or Foreign Housing Deduction.
These provisions can provide additional tax benefits for certain qualified housing expenses incurred while living abroad.
Depending on where a taxpayer lives, the housing benefit can substantially increase the overall tax savings available beyond the basic Foreign Earned Income Exclusion. The applicable housing limits can also vary by foreign location.
The Foreign Housing Exclusion generally applies to amounts provided by an employer, while qualifying self-employed individuals may instead be eligible for the Foreign Housing Deduction. These benefits are calculated on Form 2555.
When the FEIE Is Often More Advantageous
The FEIE may be particularly beneficial when:
- The taxpayer lives in a low-tax or no-tax country
- Foreign income taxes paid are minimal or zero
- Income consists primarily of earned income
- The taxpayer qualifies for additional foreign housing benefits
The FEIE can also affect adjusted gross income and other calculations on the U.S. tax return. However, taxpayers should not assume that reducing taxable income automatically makes the FEIE the best long-term choice.
What Is the Foreign Tax Credit (FTC)?
The Foreign Tax Credit generally provides a dollar-for-dollar credit against U.S. income tax for qualifying foreign income taxes paid or accrued to a foreign country.
Key features of the FTC include:
- Can apply to both earned income and passive income
- Generally claimed using Form 1116 by individuals
- The credit is limited based on the amount of U.S. tax attributable to foreign-source income
- Unused foreign tax credits can generally be carried back one year and carried forward for up to 10 years, subject to the applicable rules and limitations
- Often works particularly well when foreign income tax rates are similar to or higher than U.S. income tax rates
Rather than excluding income, the FTC generally allows the income to remain part of the U.S. tax calculation while providing a credit for qualifying foreign income taxes already paid or accrued.
You Cannot Double-Dip
Taxpayers may sometimes use both the Foreign Earned Income Exclusion and Foreign Tax Credit on the same tax return, but they cannot receive both tax benefits on the same income.
Foreign income taxes attributable to income excluded under the FEIE generally cannot also be used to claim a Foreign Tax Credit.
However, taxpayers with foreign earned income exceeding the FEIE limit may potentially claim a Foreign Tax Credit for qualifying foreign taxes attributable to income that was not excluded.
Determining the most advantageous combination can require careful calculations and planning.
When the Foreign Tax Credit Is Often More Advantageous
The FTC may be particularly beneficial when:
- The taxpayer lives in a relatively high-tax country
- Foreign income tax rates are similar to or higher than U.S. rates
- The taxpayer has passive foreign income
- The taxpayer has foreign taxes that may generate usable credit carryovers
- Long-term tax efficiency is more important than simply minimizing the current year's taxable income
- Future income and retirement planning are considerations
In many higher-tax jurisdictions, the Foreign Tax Credit can produce better long-term results than the FEIE.
Unused foreign tax credits may also provide future value through the carryover provisions. A strategy that minimizes U.S. tax this year is not necessarily the strategy that minimizes taxes over many years.
Why the Wrong Choice Can Cost Thousands
Many taxpayers assume that the Foreign Earned Income Exclusion is automatically the better choice because it excludes income from U.S. taxation.
That is not necessarily true.
For someone living in a country with little or no income tax, the FEIE may provide substantial benefits because there may be few foreign taxes available to claim as credits.
For someone living in a higher-tax country, however, the Foreign Tax Credit may eliminate much or all of the U.S. income tax on the foreign income while potentially preserving unused foreign tax credits for other years.
Common Mistakes
Some of the most common international tax mistakes include:
- Assuming that living outside the United States eliminates the requirement to file a U.S. income tax return
- Automatically claiming the FEIE without determining whether the FTC would produce a better result
- Believing that the FEIE eliminates self-employment tax
- Overlooking the Foreign Housing Exclusion or Foreign Housing Deduction
- Attempting to claim a Foreign Tax Credit for taxes attributable to income already excluded under the FEIE
- Forgetting that separate international information-reporting requirements may apply even when little or no U.S. income tax is due
For example, taxpayers may have separate reporting obligations involving the Foreign Bank Account Report (FBAR) or Form 8938 under FATCA, depending on their foreign financial accounts and assets.
Final Thoughts
The Foreign Earned Income Exclusion and the Foreign Tax Credit are both valuable tools for reducing double taxation, but they serve different purposes. There is no universal "best" choice.
The right strategy depends on where you live, the taxes imposed by that country, your sources of income, and your long-term financial goals.
A decision that produces the lowest U.S. tax bill this year may not provide the greatest savings over the next five or ten years. Careful planning before filing a return can often save taxpayers thousands of dollars over time.
The article is meant for informational purposes only. Please contact me directly to discuss how this applies to your individual tax situation.