NONCASH CHARITABLE DONATIONS: WHAT TO KNOW FOR 2026
Cleaning out a closet or donating furniture to a thrift store can support a good cause and might produce a tax deduction. But the IRS requires records supporting both what you gave and what it was worth.
WHO CAN CLAIM A DEDUCTION?
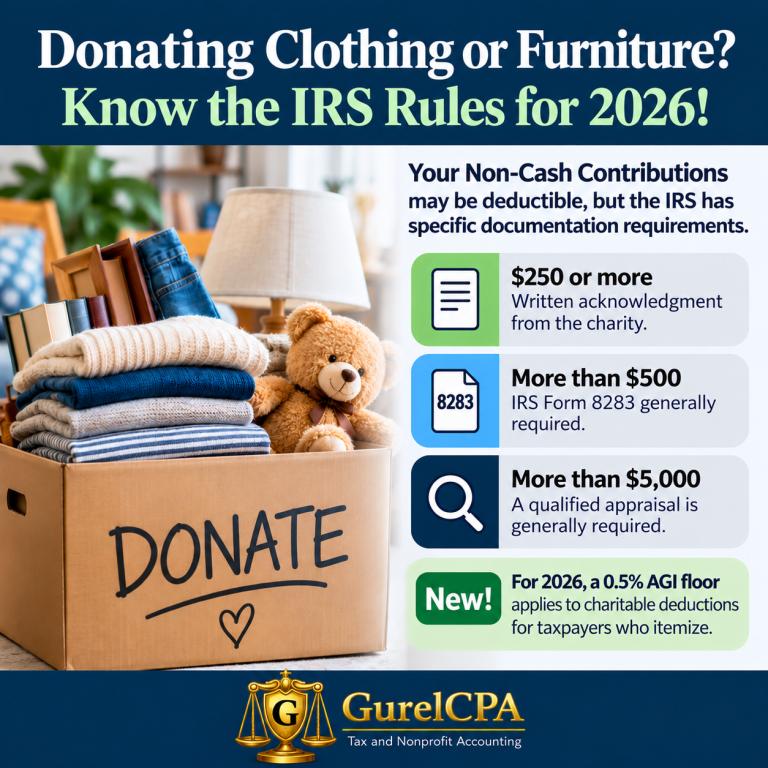
For 2026, noncash charitable contributions are deductible only if you itemize on Schedule A. A new deduction for non-itemizers covers certain cash gifts, not clothing, furniture, or other property. Also beginning in 2026, itemizers generally deduct charitable contributions only to the extent their total qualifying contributions exceed 0.5% of adjusted gross income (AGI), subject to other limits.
WHAT IS THE DONATION WORTH?
Used clothing, books, furniture, and household goods are valued at fair market value: what a willing buyer would pay for them in their current condition, not what you originally paid. Comparable thrift-store or resale prices can help. Clothing and household items generally must be in good used condition or better, with a narrow appraised-property exception.
THE IRS DOCUMENTATION THRESHOLDS
Under $250: Keep a charity receipt and your own itemized valuation records. A limited exception applies when a receipt is impractical.
$250 or more for one contribution: Get a written acknowledgment from the charity describing the property and stating whether anything was received in return.
More than $500 in total noncash deductions: Generally attach IRS Form 8283, Section A, and keep additional records. Smaller donations count toward the total.
More than $5,000 for an item or similar-property group: Generally obtain a qualified appraisal and complete Form 8283, Section B. Similar items given to different charities are combined; exceptions apply.
A FEW EXAMPLES
If you donate $150 of clothing, keep an itemized list and receipt. A single $300 furniture donation requires the charity’s qualifying written acknowledgment. If your donations total $650 for the year, Form 8283 is generally required. Donating $3,000 of books to one charity and $2,500 of books to another generally triggers the appraisal rule for similar property.
MAKE YOUR RECORDS EASY TO DEFEND
List the donated items, their condition, and reasonable secondhand values; take photographs; and retain the charity’s acknowledgment. The charity should not assign a value—that is your responsibility. Donations must go to qualifying organizations; gifts directly to individuals are not deductible. Vehicles, securities, art, and certain other property have special rules.
THE BOTTOM LINE
For 2026, remember $250 for a written acknowledgment, more than $500 for Form 8283, and generally more than $5,000 for a qualified appraisal. Good records made on donation day are the best protection at tax time.
The article is meant for informational purposes only. Please contact me directly to discuss how this applies to your individual tax situation.