What Counts as “Earned Income” for the Foreign Earned Income Exclusion?
Many U.S. taxpayers living abroad assume that if they qualify for the Foreign Earned Income Exclusion (FEIE), all of their income is excluded.
That is not correct.
The FEIE applies only to qualifying foreign earned income. Investment income, retirement income, and capital gains generally do not qualify. Understanding the distinction can prevent costly mistakes.
What Is Earned Income?
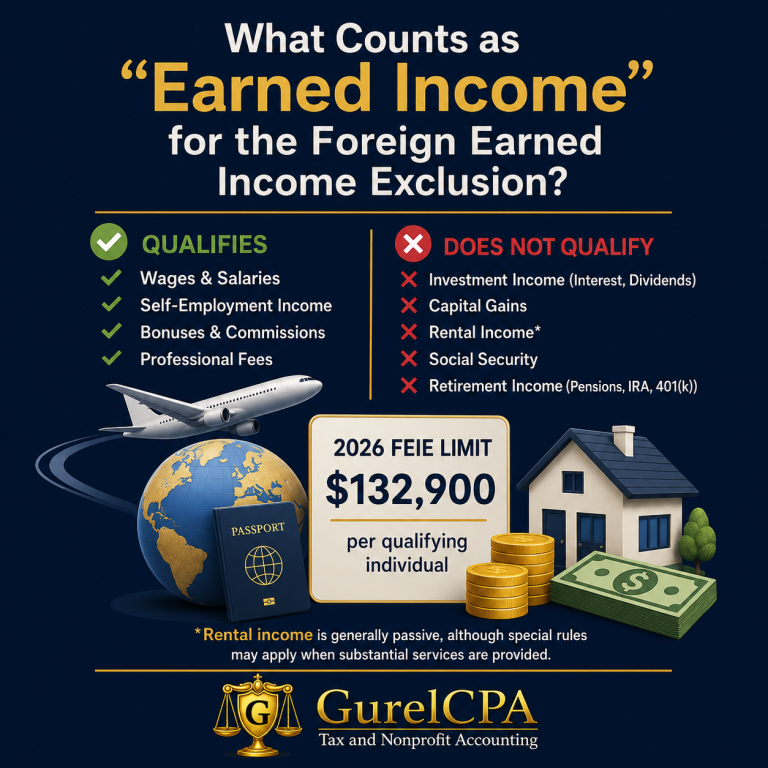
For FEIE purposes, earned income generally means compensation for personal services you perform in a foreign country. Examples include:
- Wages and salaries
- Bonuses and commissions
- Professional fees
- Tips
Business and self-employment income can also qualify, but special rules determine how much of business profit is treated as earned income.
Where You Perform the Work Matters
The source of earned income is generally determined by where you perform the services, not by where your employer is located or where you are paid. For example, compensation for work performed in France can be foreign earned income even if the employer is in the United States and the pay is deposited into a U.S. bank account.
What Is Not Earned Income?
The following types of income generally do not qualify for the Foreign Earned Income Exclusion:
- Interest from bank accounts and other investments
- Dividends from stocks and mutual funds
- Capital gains from stock, cryptocurrency, or real estate sales
- Social Security benefits
- IRA and 401(k) distributions
- Pension and annuity income
Living overseas does not convert passive or retirement income into earned income.
Rental Income Requires a Closer Look
Rental income should not automatically be treated as either earned or unearned income for FEIE purposes. The IRS classifies rents as variable income. Depending on the facts and the services you provide, rental income may be earned income, unearned income, or partly both.
Qualifying for the FEIE
Having foreign earned income by itself is not enough. To claim the FEIE, you must have a tax home in a foreign country and meet either the bona fide residence test or the physical presence test.
For 2026, the maximum Foreign Earned Income Exclusion is $132,900 per qualifying individual. The actual exclusion may be lower depending on the amount of foreign earned income and the portion of the year for which you qualify.
A Simple Example:
Assume a qualifying taxpayer living and working abroad earns:
- $110,000 in foreign wages
- $20,000 in dividends
- $15,000 in capital gains
The $110,000 of wages may qualify for the Foreign Earned Income Exclusion. The dividends and capital gains do not qualify for the FEIE and remain subject to the normal U.S. tax rules.
One Important Point for Self-Employed Taxpayers
A qualifying self-employed taxpayer may claim the FEIE on qualifying foreign earned self-employment income. However, the FEIE generally reduces regular U.S. income tax, not self-employment tax. A Social Security totalization agreement may affect the self-employment tax result in some countries.
The Bottom Line
The FEIE is based on income from services performed in a foreign country. It does not provide a blanket exclusion for all income simply because a U.S. taxpayer lives abroad.
The distinction between earned, unearned, and variable income can be especially important for taxpayers who have a combination of wages, self-employment income, investments, retirement income, or rental activity.
The article is meant for informational purposes only. Please contact me directly to discuss how this applies to your individual tax situation.